Greensboro, NC · Guilford County
Medicare Supplement plans in Greensboro
Medigap fills the gaps Original Medicare leaves: deductibles, coinsurance, and the bills that surprise people. Here is what Plan G and Plan N cover, what they tend to cost here, and the enrollment window you do not want to miss.
Free consultation. No obligation to enroll.
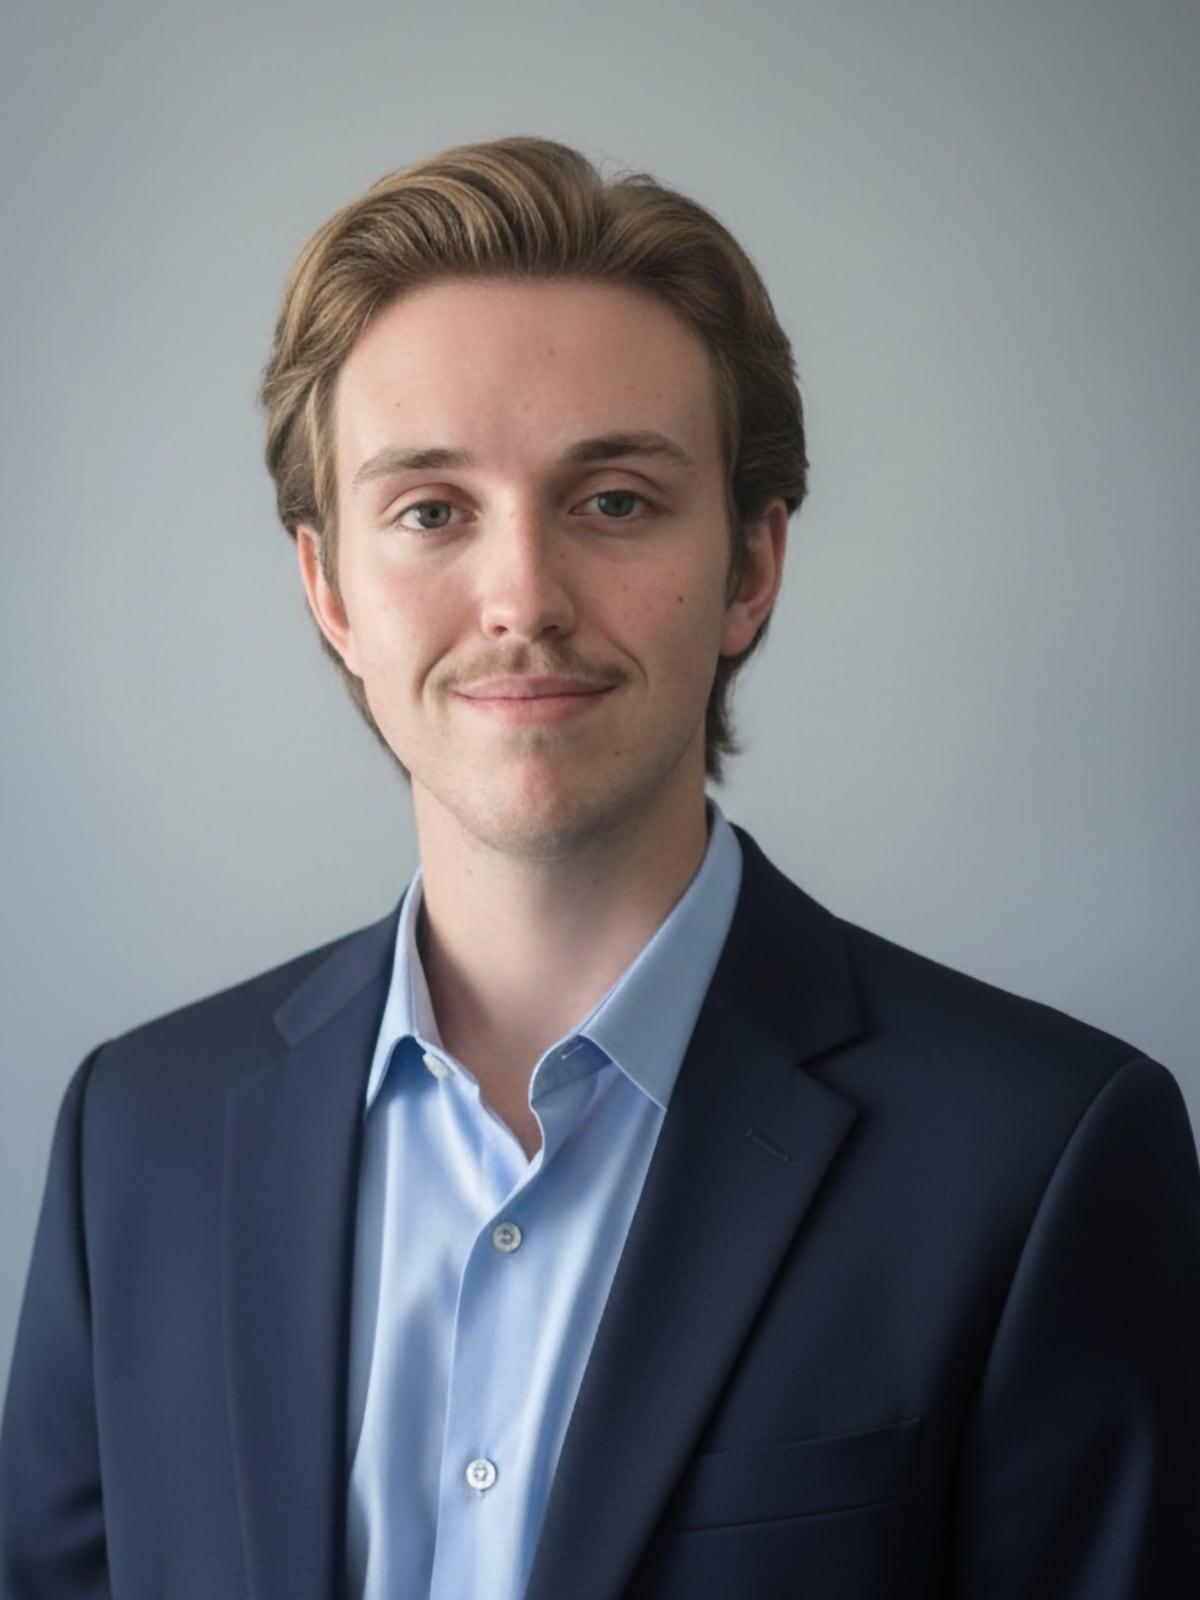
- Licensed agent · NC Life & Health
- One local person, not a call center
- Meet at home, nearby, or by phone
- Free consultation. No obligation.
The plans people actually buy
Medigap plans are standardized. A Plan G is a Plan G no matter which insurer sells it: same benefits, set by the federal government. That makes comparing them simpler than most insurance shopping. You compare premiums and companies, not coverage.
- 1
Plan G: the most complete
Plan G covers nearly everything Original Medicare does not, except the Part B deductible. You pay the yearly Part B deductible yourself, then Plan G picks up the rest of the approved costs: hospital coinsurance, skilled nursing, doctor coinsurance, foreign travel emergencies, and more. It is the most popular Medigap plan in North Carolina for people who want predictable costs.
- 2
Plan N: lower premium, small copays
Plan N costs less per month than Plan G. In exchange, you pay the Part B deductible, plus copays of up to $20 for some office visits and up to $50 for emergency room visits that do not lead to admission. If you rarely see the doctor, Plan N can be the better value. If you go often, the copays add up.
- 3
Other plans: mostly legacy
Plans A, B, C, D, F, K, L, and M still exist, but most are legacy options. Plan F is only available if you were eligible for Medicare before January 1, 2020. For most people turning 65 now, the real choice is G versus N.
What it costs, honestly
For a 65-year-old in the Greensboro area, Plan G runs roughly $130 a month. That is an approximation from published ranges, not a quote for you. Your price depends on the insurer, your age, whether you use tobacco, and available discounts. Plan N runs meaningfully less per month, with the copay tradeoff described above.
Two things matter more than the starting premium: how the insurer raises rates over time, and the company behind the policy. A cheap Plan G from a company with steep annual increases is not the bargain it looks like in year one. I will show you real quotes and rate histories so you can see the full picture.
Remember: Medigap does not include drug coverage. You pair it with a separate Part D plan, which is its own comparison. How Part D works in 2027.
The window that protects you
Your six-month Medigap open enrollment period begins when you are 65 or older and enrolled in Part B. During it, any insurer selling Medigap in North Carolina must sell to you at the best available rate for your age, no matter your health.
After it ends, insurers can ask health questions and turn you down. That is why the Advantage-versus-Medigap decision deserves real thought the first time: the Greensboro comparison. If you are inside your window now, do not wait.
Medicare help in your community
Questions people ask me about Medigap
- What Medigap plans are available in Greensboro?
- The standardized plans G and N are the ones most people choose here, along with the legacy plans still on the market. Because Medigap plans are standardized by the federal government, a Plan G from one insurer covers the same benefits as a Plan G from another. What differs is the premium, the company's rate history, and how they handle claims.
- How much does Plan G cost in Greensboro?
- For a 65-year-old in the Greensboro area, Plan G premiums are roughly $130 a month, but that is an approximation, not a quote. Your actual premium depends on the insurer, your exact age, tobacco use, and discounts. The only way to know your price is a real quote, which I can help you get at no cost.
- Plan G vs. Plan N: which should I pick?
- It comes down to how often you see the doctor. Plan G costs more monthly and almost nothing when you need care. Plan N costs less monthly, but you pay the Part B deductible plus copays per visit. If you are in and out of offices, G usually wins. If you are healthy and rarely go, N can save money. We can run your actual numbers.
- When is the best time to buy a Medigap policy?
- During your six-month Medigap open enrollment period, which starts when you are 65 or older and enrolled in Part B. During those six months, insurers must sell you any policy they offer regardless of your health. After it ends, they can ask health questions and decline you in most situations. Do not let this window pass without deciding.
- Can I get help comparing Medigap plans?
- Yes. I will pull real quotes from the insurers I represent, explain what each covers, and tell you where to look for the rest. The comparison is free, with no obligation to buy. Call or text (919) 408-6671.
Christian BrinkleyNC Life & Health · Greensboro, NC
Let's get your real numbers
I will pull actual Medigap quotes for your age and zip code, explain the differences, and help you decide before your window closes. Free, no obligation. Call or text (919) 408-6671.
Free consultation in person or by phone. It’s me who answers. Calls and appointments 9am to 5pm, Monday through Saturday, Eastern time.