Greensboro, High Point & Winston-Salem
Coordinate retirement income with Medicare
Retiring can change where your monthly income comes from and what you pay for Medicare. I can help Triad households in Greensboro, High Point, and Winston-Salem understand the Medicare questions and work with an advisor for financial planning.
Free consultation. No obligation to enroll.
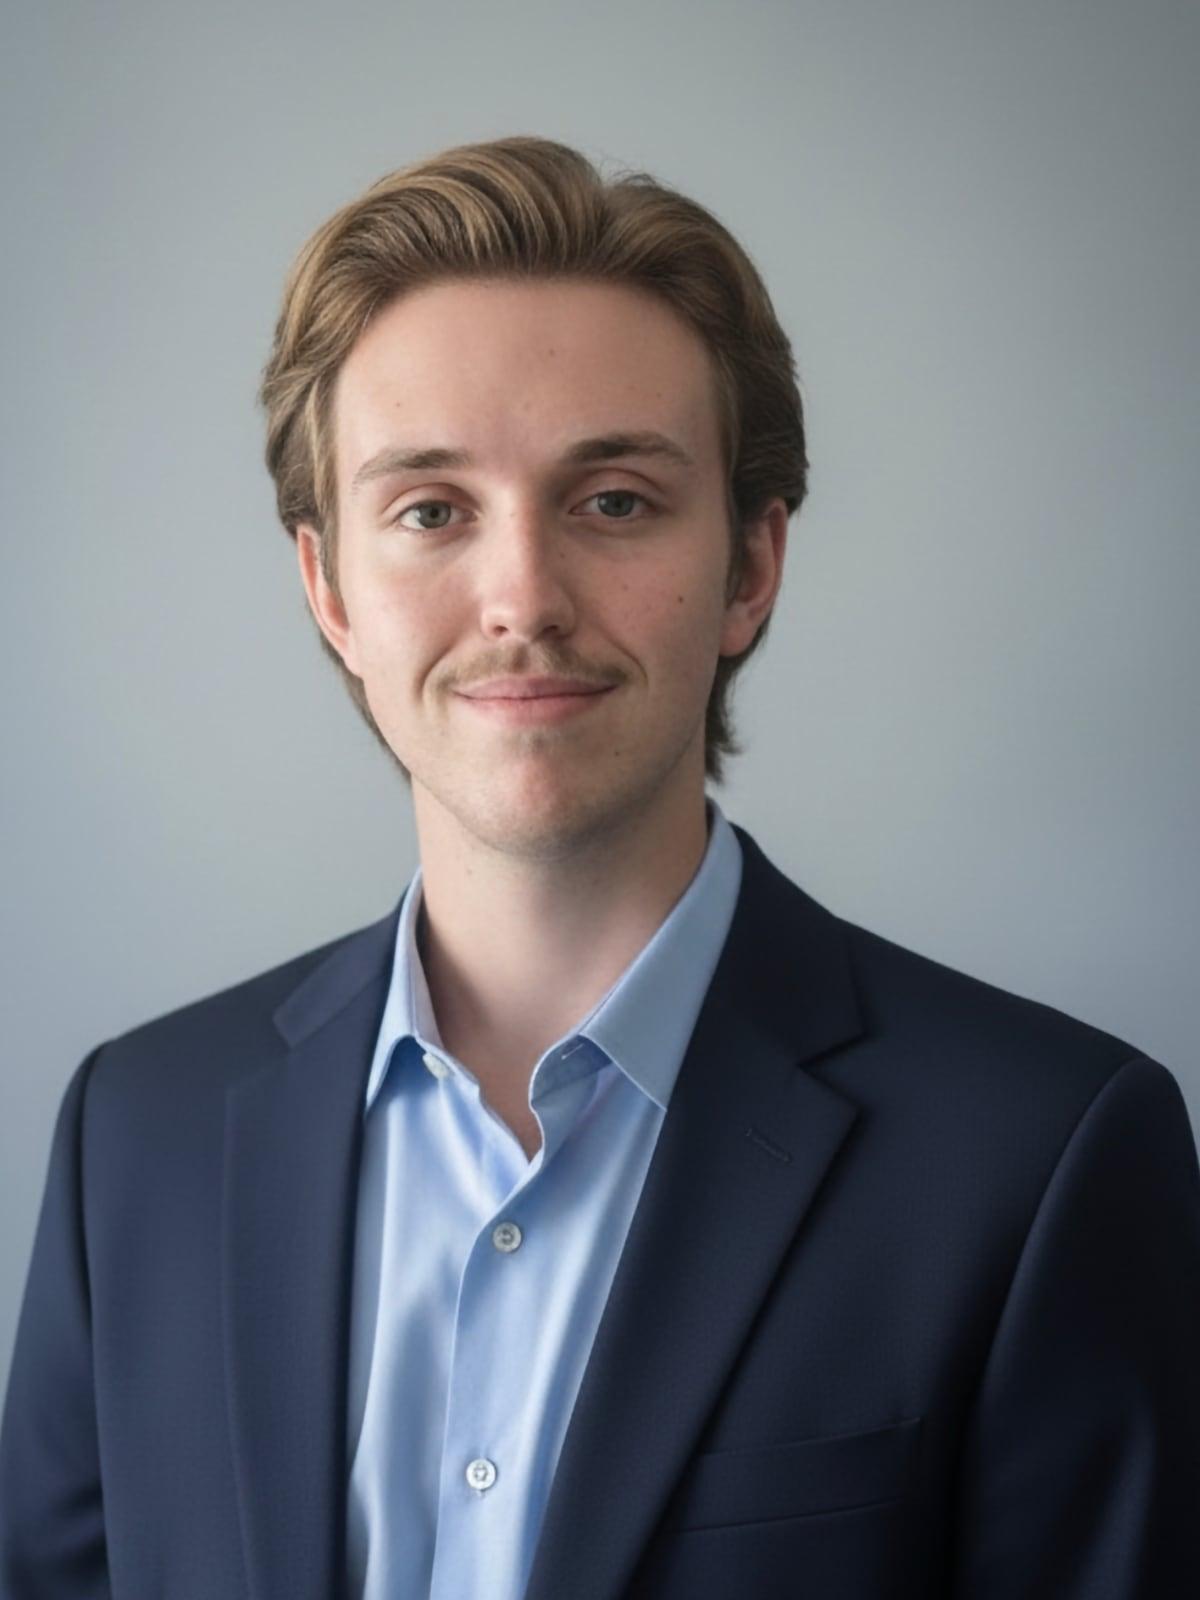
- Licensed agent · NC Life & Health
- One local person, not a call center
- Meet at home, nearby, or by phone
- Free consultation. No obligation.
The four options
- 1
Leave it where it is
Your former employer’s plan may let you keep the account. Review its investment options, fees, withdrawal rules, and any minimum balance requirements with the plan administrator.
- 2
Roll it to an IRA
An IRA rollover can change your investment options, fees, and account rules. Discuss those differences and the tax treatment with a qualified professional before moving money.
- 3
Roll it into a new employer's plan
An option if you’re still working somewhere whose plan takes transfers. Worth knowing about, because money in the plan where you still work can be exempt from required withdrawals in a way IRA money isn’t.
- 4
Cash it out
A cash distribution may make the taxable amount income in a single year and can affect the income Medicare reviews two years later. A CPA or registered investment adviser can help assess the consequences for your situation.
The years before required distributions
For some households, taxable income falls after work ends and before required distributions begin. The timing of withdrawals and conversions during those years may affect taxes and future Medicare premiums.
A change in retirement income may also affect what you pay for Medicare. Looking at both together can help you prepare for future costs. A qualified tax professional or advisor can assess your individual situation.
My calculator compares the estimated Medicare premium effect of two Roth conversion timing examples using 2026 rates. You can review the results with your tax professional or financial advisor.
See what the timing is worth →How I can help
I handle the part of retirement that runs on insurance: your Medicare coverage, the protection that keeps a spouse steady, long-term care, and guaranteed income options. Those decisions carry real deadlines, and the order you make them in affects what you pay.
I look at how the pieces line up, when your coverage starts, what a withdrawal does to your Medicare premium two years later, and where a guarantee is worth its cost. My accounting training at UNC Greensboro is why those connections interest me.
I sit down with you and go through your whole situation first, what you have, what you are worried about, and what is coming up. Some of it I handle myself. The rest I hand to someone who can: an investment adviser, a tax professional, an elder law attorney. You get an introduction to a specific person, not a suggestion to go find one.
My license covers insurance rather than investment management, so anyone I bring in explains their own services, qualifications, and fees before you decide to work with them.
Questions people ask
- When do required minimum distributions start?
- For many people, required minimum distributions begin at 73. The starting age is 75 for people born in 1960 or later. Your account type and circumstances can also affect the rules.
- Why review withdrawals before required distributions begin?
- For some households, the years after paychecks stop and before required distributions begin may bring lower taxable income. That can make the timing of withdrawals and conversions worth discussing with a CPA or registered investment adviser.
- How can retirement income affect Medicare costs?
- Medicare generally uses income from two years earlier to determine whether an income-related charge applies. A large taxable withdrawal or Roth conversion may affect future premiums. I can identify the questions to discuss with your tax professional or advisor.
- Is a rollover taxable?
- A direct rollover is generally not taxable at the time of transfer. Receiving the funds yourself can trigger withholding and a 60-day rollover deadline. Confirm the rules and your circumstances with the plan administrator and a qualified tax professional.
- Can you advise me on how to invest it?
- No. I hold an insurance license, not a securities license, and I am not a registered investment adviser. I can provide general education about deadlines and Medicare interactions, then identify questions for a CPA or registered investment adviser.
- How can you help with my retirement questions?
- I help you understand your Medicare and insurance options and how they relate to retirement. For financial planning, I work with an advisor. I can discuss your priorities and identify the right next steps.
- Are you a financial advisor?
- I’m a licensed insurance agent and an accounting senior at UNCG. I work with an advisor for retirement financial planning, and I can help you prepare questions for a CPA when tax advice is needed.
Local retirement and Medicare education
I offer personal Medicare and insurance help in Greensboro, High Point, Winston-Salem, and nearby communities. I can meet at your home or talk by phone. Meet directly with Christian in person or by phone.
Guilford County
Greensboro
Meet at home or talk by phone
Retirement help in Greensboro →Guilford County
High Point
Meet at home or talk by phone
Retirement help in High Point →Forsyth County
Winston-Salem
Meet at home or talk by phone
Retirement help in Winston-Salem →
Retirement help in nearby communities
Christian BrinkleyNC Life & Health · Greensboro, NC
Check how income may affect Medicare
Review the two-year income lookback and identify which questions belong with a CPA or registered investment adviser.
Free consultation in person or by phone. It’s me who answers. Calls and appointments 9am to 5pm, Monday through Saturday, Eastern time.
Your Social Security start date is another part of retirement planning. Consider your income needs, your spouse’s benefits, and other savings as you compare your options. When to take Social Security explains the main ages and questions to discuss with your advisor.